
Some families also turn to credit cards, Buy Now Pay Later (BNPL) services and instant loans through mobile applications to meet smaller wedding expenses and festive shopping costs.
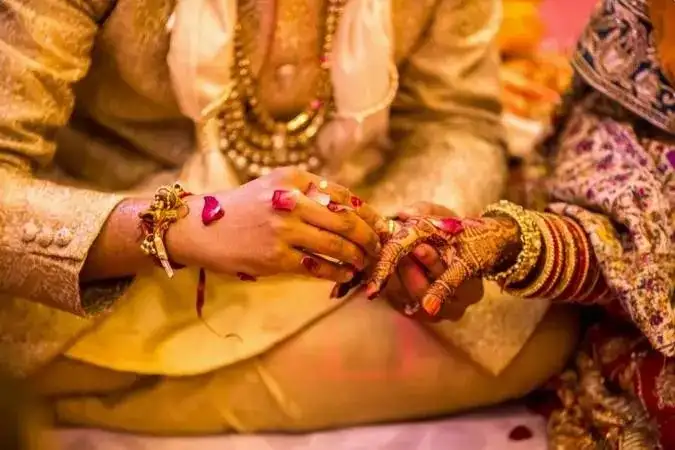
India's wedding season brings celebrations, family gatherings and elaborate ceremonies. However, rising wedding expenses are also leaving some families struggling with debt long after the celebrations end.
From a sister's wedding to a daughter's vidaai or one's own marriage, families often face pressure to meet social expectations and fulfil relatives' wishes. The fear of what others might say, coupled with the belief that a wedding happens only once, can lead people to spend beyond their financial means.
The financial burden, however, does not end when the guests leave and the wedding arrangements are taken down. For families that borrow money to meet the expenses, monthly loan repayments can continue for years.
India's wedding economy and rising expenses
Industry estimates put India's wedding economy at around ₹6.5 lakh crore, with 40 lakh to 50 lakh weddings taking place annually.
According to a recent annual wedding industry report based on a survey of more than 2,000 couples, wedding expenditure increased 8% year-on-year. The average wedding budget reached ₹39.5 lakh, while destination weddings cost an average of ₹58 lakh.
The report found that around 78% of couples funded their weddings through personal savings. However, 15.1% had to borrow money to meet the expenses.
Those who took loans borrowed an average of ₹15.5 lakh, with much of the money going towards premium venues, jewellery and catering.
Credit cards and personal loans add to financial pressure
For middle-class families, borrowing ₹15.5 lakh can mean a substantial financial commitment. While regular incomes may initially make monthly repayments manageable, circumstances such as job losses, medical emergencies or a fall in income can make the debt difficult to repay.
Some families also turn to credit cards, Buy Now Pay Later (BNPL) services and instant loans through mobile applications to meet smaller wedding expenses and festive shopping costs.
The figures point to a wider increase in household borrowing. Credit card outstanding balances in India have more than tripled in five years to around ₹2.70 lakh crore. Personal loans grew 16.7% year-on-year as of March 2025, while household debt reached a record 47.8% of GDP by December 2025.
Mumbai man's experience highlights debt trap
The case of Amit (name changed), a 38-year-old Mumbai resident, illustrates how multiple loans can lead to mounting financial pressure.
Following business losses, Amit began using his credit card to meet family expenses, including costs associated with a close relative's wedding. He later took a personal loan to clear his credit card dues.
Over time, he found himself caught in a cycle of borrowing, with 13 separate loan accounts and total outstanding debt of ₹6,22,865.
He reportedly received more than 200 recovery calls a day and faced repeated visits from recovery agents, leaving him under severe mental stress.
Later, a debt negotiation and settlement guidance company took over communication with his lenders, which significantly reduced recovery calls and home visits. Following negotiations in phases across all 13 loan accounts, his debt was settled for ₹2,22,388, a reduction of 64%.
The company maintains Amit has since been able to make a fresh start.
Published: 13 Nov 2026, 11:16 am IST
Disclaimer: Kindly avoid objectionable, derogatory, unlawful and lewd comments, while responding to reports. Such comments are punishable under cyber laws. Please keep away from personal attacks. The opinions expressed here are the personal opinions of readers and not that of Mathrubhumi.
